Imagine opening your retirement account statement and seeing something unexpected: a rental property, a business loan, or an ownership interest in a private fund. No stock ticker symbol in sight.
For many investors, that sounds like a different kind of account altogether, but it isn’t.
A self-directed IRA follows the same basic IRA tax rules as a conventional IRA, but can hold a much wider range of eligible investments. Think of it as opening doors beyond the familiar stock-and-bond market.
So what is behind those doors, and what should investors know before walking through one?
Real estate: it’s more than a house on a statement
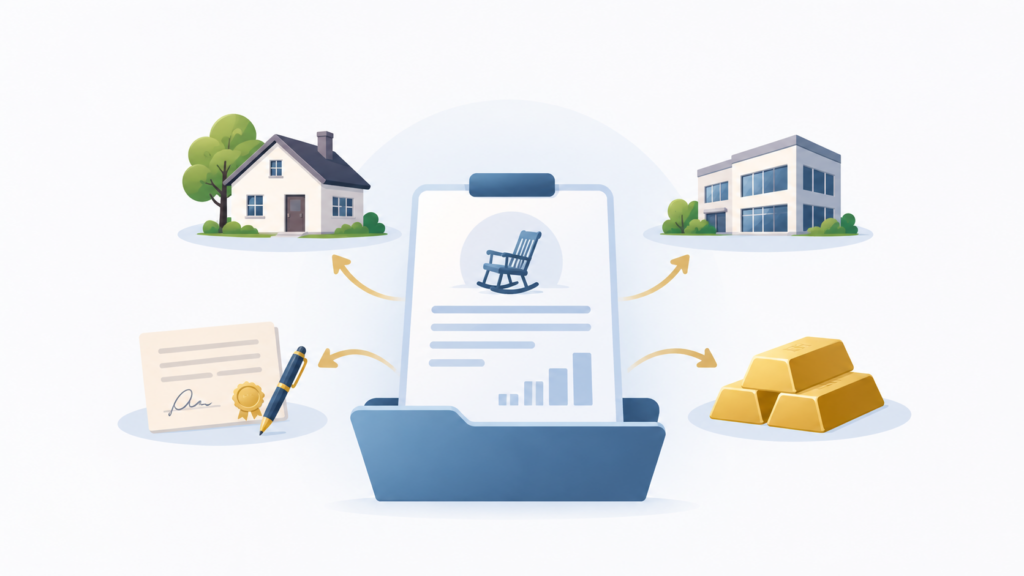
Suppose an investor wants their IRA to buy a rental property. The IRA, not the investor personally, purchases and owns it. Rent goes back into the IRA. Property taxes, insurance, repairs and other eligible expenses are paid from IRA funds. The owner cannot use the property as a vacation getaway, rent it to a disqualified family member, or pay its bills from a personal checking account.
You can also invest in commercial properties, vacant land, or real estate funds and syndications through a self-directed IRA. If you own property directly through your IRA, there’s more paperwork and administration to manage.
With a fund or syndication, a sponsor typically handles the day-to-day operations, although you’ll need to consider management fees, restrictions on accessing your money, and the sponsor’s experience and track record.
Private funds and syndications: investing alongside others
Instead of buying an entire building, an IRA might invest in a private fund that pools capital from multiple investors. Depending on the offering, that fund could own real estate, extend credit or pursue another defined strategy.
The questions shift from “Who fixes the roof?” to “Who manages the fund, when can investors get their money back, and what happens if more capital is needed?” Subscription agreements, capital calls, distributions, valuations and exit restrictions deserve close attention. The IRA must be named correctly in the investment paperwork before funding.
Private companies: a stake outside the stock exchange
Not every business sells shares on a public exchange. A self-directed IRA may hold eligible ownership interests in certain private companies or LLCs. That creates possibilities, but also potential complications involving related parties, investor control, compensation and unrelated business taxable income.
An investor considering an interest in a company they own, manage or work for should seek qualified tax and legal advice before taking action. A business being private does not automatically make the investment permissible for that person’s IRA.
Promissory notes: the IRA as lender
An IRA can sometimes invest through a promissory note, effectively providing financing to a borrower under agreed terms. The note may specify an interest rate, maturity date, repayment schedule and collateral.
A signed promise to repay is not the same as a guaranteed return. Investors need to assess borrower credit, documentation, collateral, servicing and what happens if payments stop. Lending to a disqualified person can violate IRA rules, even if the loan appears commercially reasonable.
Precious metals: the details matter
Certain qualifying coins and bullion can be held in an IRA. But “gold” is not a blanket category of approved investments: IRS fineness and product requirements apply, along with specific custody and storage rules. Investors should understand dealer spreads, storage costs and how they would eventually sell or distribute the metals.
While self-directed IRAs offer more investment options, rules still apply to what you can hold. IRAs generally cannot invest in life insurance contracts or collectibles such as artwork, antiques and most coins; specific exceptions apply to certain precious metals. Transactions involving the account owner and other disqualified persons may also be prohibited.
Eligibility is only the first test. An investment might be allowed inside an IRA yet still be unsuitable because it is difficult to value, expensive to administer, highly concentrated or impossible to sell when cash is needed. A long holding period can make those tradeoffs especially important.
The practical starting point is “What role would this investment play in my retirement plan—and what does owning it actually require?” Investors should review liquidity, fees, risk, valuation, tax considerations and ongoing paperwork with appropriate advisors before committing funds.
Preferred Trust administers self-directed retirement accounts holding eligible alternative assets. Investors choose and evaluate their own investments; Preferred Trust does not recommend specific assets or sponsors. If you are considering an investment outside the public markets, contact the Preferred Trust team early to discuss account setup, documentation and funding requirements.
This article is for educational purposes only and does not constitute tax, legal or investment advice. Consult qualified professionals regarding your individual circumstances.